Key Takeaways
Speed to power — the time from power agreement to firm energization — has replaced raw megawatt capacity as the primary site selection metric for AI data centers.
The binding constraint is no longer grid availability. Large power transformers now average 128-week lead times; medium-voltage switchgear and interconnection queues extend timelines further.
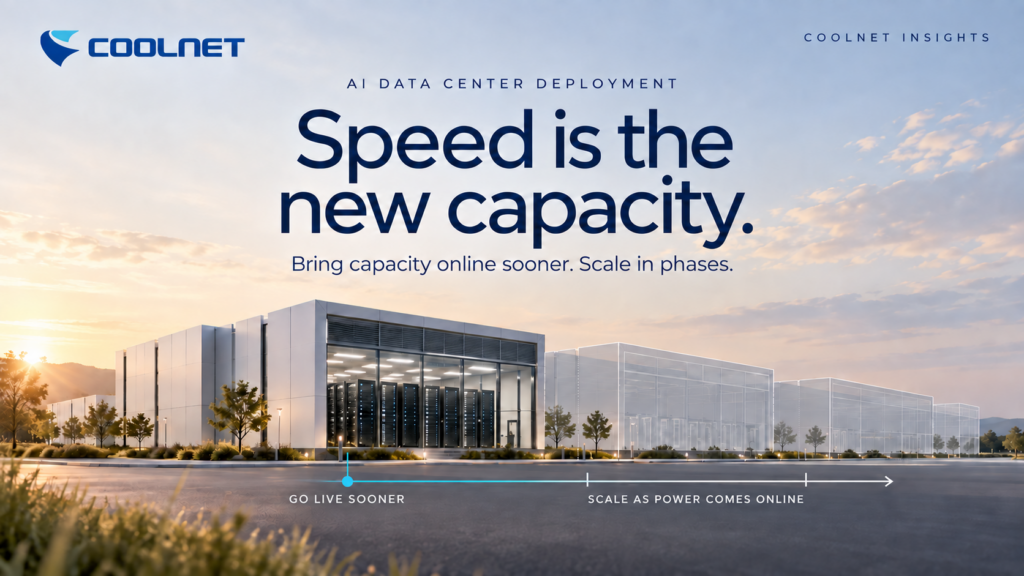
A 150 MW site that energizes in 12 months is worth more to a GPU operator than a 1 GW campus that energizes in 48 months — phased cash flow and idle-GPU cost make that math unavoidable.
The U.S. Department of Energy launched a formal Speed to Power Initiative in September 2025, confirming this is now a policy priority, not just an industry opinion.
Modular and prefabricated data center infrastructure compresses building timelines by 30–60%, enabling phased capacity delivery that matches available power — but only when the electrical supply chain is planned in parallel, not after.
For over a decade, the most important number on a data center site selection scorecard was headline megawatts: how much power could eventually be served, on the largest possible campus, at the lowest possible price per kilowatt. Bigger was better. A 1 GW reservation in a Tier 1 market was a strategic asset regardless of when it could actually be energized.
That logic broke somewhere between 2023 and 2025, and the fault lines are now impossible to ignore. A 1 GW site with a 2031 energization date is worth less to a company deploying H200 or Blackwell clusters than a 150 MW site with power on in twelve months. The new metric is not capacity. It is speed to power.
This analysis draws on Coolnetpower’s 15-plus years designing and delivering precision data center infrastructure — from containerized and micro data centers to modular power and cooling systems — for operators, colocation providers, and enterprise IT teams. The perspective here reflects patterns observed across real deployment projects, not a summary of press releases: what consistently separates projects that energize on schedule from those that slip is the sequencing of electrical procurement relative to everything else.
Table of Contents
ToggleThe Case Against the Megawatt as the Lead Metric
The conventional scorecard has two embedded assumptions. First, that capacity constrained deployment — that whoever owned the most power reserved would win. Second, that time to energization was relatively predictable and therefore not a first-order variable.
Both assumptions were credible in a world of 10–25 kW rack densities and gradual demand growth. They became obsolete the moment GPU clusters arrived. A rack running NVIDIA’s B200 NVL72 draws over 120 kW. A modest 300-rack AI cluster consumes power at a scale that would have described a mid-sized colocation campus in 2019. The speed of AI investment has compressed multi-year planning cycles into quarters.
Data Center Knowledge’s September 2026 analysis framed it this way: even a site that can eventually deliver 1 GW provides zero value during the years it takes to get there. The operator bidding for GPU colocation contracts in 2025 cannot wait until 2029 for power. The contract window closes, the customer finds another option, and the stranded reservation becomes a liability.
The U.S. Department of Energy has made the shift official. The DOE Grid Deployment Office launched its Speed to Power Initiative in September 2025, soliciting input from utilities, grid operators, and developers on how to accelerate multi-gigawatt generation and transmission projects specifically for AI data center load. When a federal agency names a market dynamic in a policy initiative, the industry’s earlier informal consensus has become consensus.
Key Takeaway: Megawatt capacity describes a ceiling. Speed to power describes a delivery date. For AI deployments, only one of those numbers generates revenue.
From our own project experience, the projects that slip least are rarely the ones with the most favorable interconnection position. They are the ones where the transformer and switchgear orders were placed before the site was even shortlisted — a counterintuitive discipline most planning playbooks still treat as premature.
What Is Actually Slowing Projects Down
The reflexive diagnosis is that grids are overwhelmed. That is partially true but increasingly incomplete. The binding constraint on speed to power has migrated from the utility’s interconnection queue into the global supply chain for electrical equipment.
Large power transformers are the clearest example. Before 2020, a major transformer could be ordered and delivered in roughly 50 weeks — under a year. According to CISA supply chain data cited across multiple industry analyses, average lead times have now stretched to approximately 128 weeks for standard units, with high-capacity custom equipment running four to five years. The implication, stated directly by Global Data Center Hub in September 2026, is that transformer procurement must precede land acquisition on the project timeline. The factory queue is the critical path, not the planning department.
Medium-voltage switchgear and generator step-up units have followed the same trajectory. Wood Mackenzie’s Q2 2025 survey, cited in Manufacturing Magazine’s analysis of substation gear constraints, found that switchgear lead times for AI-relevant applications had moved from months to multi-year timelines, making energization impossible regardless of how quickly the building shell could be completed.
The Turner & Townsend 2025–2026 Datacenter Construction Cost Index surveyed project teams directly: nearly half identified power access as the single biggest scheduling constraint, ahead of labor, permitting, and land. Grid connection wait times in congested U.S. markets now reach seven years in some cases.
The current bottleneck map looks like this:
Constraint category | Typical pre-2020 timeline | 2025–2026 reality | Primary impact |
|---|---|---|---|
Large power transformers | ~50 weeks | 128 weeks average; 4–5 years for high-capacity | Energization date |
MV switchgear and breakers | Months | Multi-year, allocation-dependent | Energization at every phase |
Interconnection queue | 2–4 years | Up to 7 years in congested U.S. markets | Firm utility power |
Building shell (modular approach) | 24–36 months | 3–13 months with prefabrication | Compute readiness |
Permitting and land | Variable | Still variable | Civil start |
The important observation is that the building itself is no longer the slowest element on this list. Prefabrication has addressed that. The slowest elements are electrical and regulatory — and those require a different set of interventions than faster construction.
Industry estimates suggest that 30–50% of planned U.S. data center capacity is currently exposed to some form of electrical equipment delay, according to KXY Group’s analysis of the switchgear and transformer shortage. That number is not recoverable through faster concrete pours.
Why 100–200 MW Now Outperforms 1 GW Later
The financial logic of phased, faster deployment is straightforward but worth making explicit, because it runs counter to the intuition that larger commitments create greater competitive advantage.
Revenue timing dominates cost-per-megawatt analysis. A 150 MW block that energizes in month 12 begins generating colocation or cloud revenue while its 1 GW counterpart is still in procurement hold. Discounted cash flow analysis, applied at any reasonable discount rate, heavily favors the earlier start — even if the eventual cost per kilowatt is higher for the smaller build.
Idle GPU cost is not a rounding error. GPU servers ship in weeks, while facilities take 24–36 months through conventional construction. ModulEdge’s deployment timeline analysis quantifies the cost of idle GPU months at $4–14 million depending on configuration. An operator whose facility is delayed while hardware sits in staging incurs that cost daily, and it is not recoverable.
Phased builds carry less execution risk. A 150 MW block is less complex to permit, power, cool, and commission than a 1 GW campus. Each phase provides operational data that informs the next. If market demand shifts — and in AI infrastructure, it shifts rapidly — a phased operator can pause or redirect far more easily than one locked into a multi-year megacampus construction commitment.
The conclusion is not that large campuses are obsolete. They remain necessary for hyperscale operators with long planning horizons and the capital to pre-position. The conclusion is that the evaluation framework has changed. A site’s value proposition now requires a speed-to-power schedule alongside its ultimate capacity figure. Capacity without a timeline is an aspiration, not an asset.
The Counterargument That Actually Matters
The strongest objection to speed-to-power framing is this: modular prefabricated construction compresses the building timeline, but it does not fix the interconnection queue or the transformer shortage. If the electrical supply chain is still 128 weeks, a faster building does not produce faster power.
This is correct as a statement about individual interventions. It is incomplete as a strategic response.
The argument for modular and prefabricated infrastructure in a speed-to-power world is not that it eliminates electrical bottlenecks — it does not. The argument is that it removes the building from the critical path, which reveals the electrical constraints more clearly and earlier, and creates the conditions for a different kind of project sequencing.
A conventional project plans the building first and worries about transformer procurement as a follow-on. A speed-to-power project inverts that sequence: lock the transformer order, size the building around available power increments, and use modular delivery to match the facility to what the grid can actually serve — phase by phase.
KAYTUS demonstrated this logic at ISC 2026 with a fully factory-prefabricated solution scaling from 3 MW to 1 GW in standardized modules, with six-month end-to-end delivery claims for individual phases. Vertiv documented a similar approach in Dublin, where a hyperscale cloud provider deployed 60 MW within a 20-week timeframe using prefabricated modular infrastructure, per STL Partners’ modular data center analysis.
The pattern is consistent: modular delivery enables an operator to start with the power that is available now, generate revenue immediately, and expand in standardized increments as additional electrical capacity comes online. The 1 GW endpoint is still reachable — it just arrives as a sequence of fast blocks rather than as one slow build.
What Modular Infrastructure Actually Delivers on the Speed-to-Power Requirement
Modular and prefabricated data center solutions compress three specific elements of the project timeline: parallel workstreams, factory-controlled quality, and standardized commissioning.
Parallel workstreams are the primary schedule mechanism. Conventional construction is sequential: civil, structural, mechanical, electrical, and commissioning run in a chain. Prefabricated modules are built and tested at the factory while civil preparation and utility infrastructure proceed on-site. Industry data from CMIC Global’s 2026 data center construction trends analysis shows that highly modularized projects achieve schedule reductions of 30–50% compared to conventional builds, compressing what was a 24–36 month conventional timeline to 16–20 months or less.
For smaller initial phases — the 2–10 MW “first block” scenarios that now define speed-to-power proposals — the compression is even greater. Prefabricated containerized data centers like Coolnetpower’s MetaCuber containerized solution integrate racks, UPS, power distribution, cooling management, monitoring, and fire suppression in a factory-completed enclosure. On-site work reduces to civil preparation, utility connection, and commissioning — a timeline measured in weeks for the building itself, not months.
Scalable phased expansion is the second structural advantage. Rather than designing for the ultimate campus configuration on day one, a modular data center approach allows standardized power, cooling, and IT modules to be replicated in defined increments as power availability grows. Each increment is factory-configured, tested before shipment, and installable without disrupting operating infrastructure.
The Micro Data Center Deployment Playbook for AI-Ready Edge documents the operational requirements for this phased pattern: standardizing on a small number of module SKUs to avoid custom engineering per site, freezing the single-line diagram early enough to place binding electrical orders, and using pilot sites to validate commissioning scripts before broader rollout. These are operational disciplines, not just product specifications.
Pro Tip: The decision to go modular or prefabricated is most valuable when made at the same time as the electrical procurement decision — not after. Modular building timelines and transformer lead times need to be managed on the same schedule, or the faster building simply waits at the finish line for power.
It is worth stating plainly what modular and prefabricated infrastructure does not solve. It does not shorten transformer lead times, and it does not move a project up the interconnection queue. For deployments where the confirmed power increment is large and the electrical supply chain is the hard limit, a faster building shell delivers no additional speed to first revenue — the constraint simply migrates. Operators should also weigh the trade-offs modular designs introduce: less floorplan flexibility per module, a need to standardize on a limited set of SKUs, and a dependency on factory capacity that becomes its own bottleneck during peak demand. Modular is a sequencing tool, not a universal answer.
The New Pitch Is Not Your UPS Spec — It Is Your First-Block Timeline
For infrastructure suppliers — colocation providers, modular data center manufacturers, electrical contractors, and equipment vendors — the speed-to-power shift reframes what buyers actually evaluate during an RFP process.
The old pitch: “Our UPS delivers 500 kVA with 99.999% uptime across a 1 GW campus.”
The new pitch: “We can deliver the first 2 MW block within the available utility capacity, commission it within a defined timeline from contract signing, and scale it to 10 MW in standardized phases as additional power comes online.”
The distinction is not cosmetic. The buyer evaluating an RFP in 2026 is looking at three practical questions:
When can the first rack go live? Not the ultimate campus, the first usable increment.
What is the procurement risk on long-lead electrical equipment? Has the supplier pre-positioned transformer orders, and what is the actual energization schedule?
How does the solution scale without a full rebuild? Can power, cooling, and IT capacity be added in defined blocks, with clear lead time and cost per block?
The suppliers and operators who can answer these questions with specific numbers — not marketing ranges — are positioned to win AI infrastructure contracts. Those who lead with headline megawatts and ultimate campus specs will find that buyers have moved on.
The modular vs. stick-built analysis is no longer a theoretical exercise. It is the decision framework that project directors, facilities VPs, and procurement teams are running through for every AI data center expansion decision right now.
Speed to Power Requires a Different Project Sequence
The strategic implication is not simply “buy modular infrastructure.” It is that the project planning sequence itself needs to change.
A speed-to-power project starts with three questions that conventional projects treat as mid-stage concerns:
What power can we guarantee on a specific date, from existing infrastructure or confirmed procurement?
What is the procurement lead time for the critical electrical equipment at this scale, and has that order been placed?
What is the smallest commercially viable first phase that can operate on the confirmed power, and how does it scale from there?
Answering these before finalizing site selection, before locking the building design, and before committing full capital is what separates a fast project from a capacity reservation that sits on paper for three years.
For modular infrastructure providers, phased deployment options starting from the first 2 MW block represent the practical entry point into this project logic. The technical question is what power is confirmed. The commercial question is what revenue can that power support. Everything else follows from those two numbers.
The capacity-first paradigm dominated data center planning because capacity was genuinely the scarce resource. In an AI infrastructure cycle where transformer factories are running four to five years behind and interconnection queues stretch to seven years, time has become the scarce resource. Whoever delivers usable power fastest earns the rack, the contract, and the market position.
That is the shift. It is structural, it is supported by federal policy, and it is visible in the procurement decisions being made right now across the U.S. market.
Disclosure: This article is published by Coolnetpower, a provider of data center infrastructure including the containerized and modular solutions referenced above. Data points on transformer, switchgear, and interconnection lead times are drawn from the industry sources linked inline (U.S. Department of Energy, CISA supply chain data, Wood Mackenzie, Turner & Townsend, and others) and should be verified against the latest published figures for any active procurement decision. Last updated: September 2026.
If you are scoping a phased AI data center deployment and need to understand the realistic timeline from contract to first energized rack, our infrastructure team works through this sequence with operators, colocation providers, and enterprise IT teams. Book a technical fit call to map your specific power window to a deployment configuration.